Cost of Living
Renting vs. Buying a House in India in 2026: Which Makes More Financial Sense?
Written by
Ishika Pannu
Read Time
14 min read
Posted on
October 9, 2026
Overview
Overview
Renting vs. Buying a House in India in 2026: Which Makes More Financial Sense?
Buying a house is often seen as a major financial milestone in India. For many families, owning a home represents stability, independence and years of hard work. Renting, on the other hand, is sometimes treated as money spent without building anything for the future. But is that really the whole picture?
In 2026, the renting vs. buying debate is about more than comparing monthly rent with a home loan EMI. Buyers need to account for down payments, registration charges, maintenance and the cost of keeping money tied up in property. Renters need to consider rent increases, housing security and what they do with the money they save by not buying. Both choices have financial and personal advantages, and the better option depends on your circumstances.
Renting vs. Buying: What Is the Real Difference?
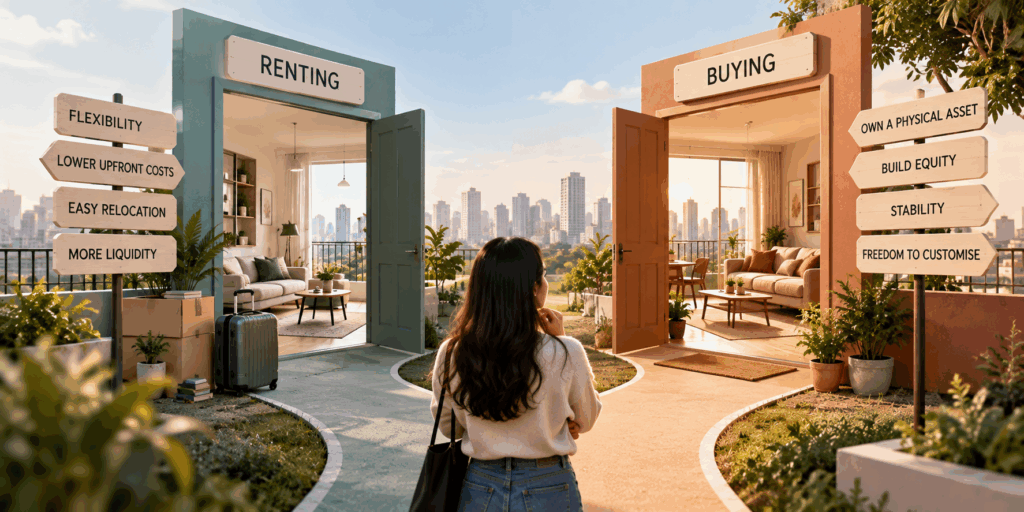
The simplest way to compare renting and buying is to understand what each option offers in return for your money. When you rent a house, you pay for the right to live in it without taking on the full financial responsibility of ownership. You can generally relocate more easily, avoid a large down payment and keep more money available for other goals. However, rent payments do not build ownership in the property.
When you buy a house, you acquire an asset and gradually build home equity as you repay your loan principal. You also take responsibility for maintenance, ownership costs, loan obligations and the possibility that the property’s market value may fluctuate.
Neither option automatically creates more wealth. A home can appreciate, but it can also underperform other investments. Renting can leave money available for investments, but that advantage matters only if you manage the money thoughtfully.
The more useful question is not simply whether renting is cheaper than buying. It is whether the total cost of housing and the benefits of each option align with your financial goals and plans.
The Hidden Costs of Buying a House in India
A common mistake is comparing monthly rent with the EMI of a property and assuming that the lower number represents the better financial decision. Buying a house involves several expenses beyond the loan repayment, and these can significantly affect how much money you need upfront and over the years.
The down payment and purchase costs
Home loans generally require buyers to contribute part of the property’s cost themselves. For example, a 20% down payment on a ₹1 crore property would require ₹20 lakh upfront, before additional purchase expenses. That money could otherwise remain available for emergencies or be invested elsewhere.
Buyers must also account for stamp duty and registration fees, which vary by state and transaction. Brokerage, legal charges, furnishing, interiors and initial repairs can add to the amount needed before the property is ready to live in. These costs are important because they reduce the amount of money a buyer has available for other financial goals.
Maintenance and home loan interest
Owning a home also means budgeting for repairs, maintenance, insurance where applicable and property-related charges. These expenses can arise even when the property is not being used, and they should be included when estimating the long-term cost of ownership.
A home loan EMI includes both principal and interest. The principal repayment gradually builds your ownership equity, while interest is a financing cost. Over a long repayment period, the total interest paid can be substantial, particularly when the loan amount is large.
This is why buyers should calculate the total cost of ownership rather than looking only at the EMI.
When Renting Makes More Financial Sense
Renting can be a sensible choice when buying would put too much pressure on your finances or when you are not ready to settle in one location. It can also make it easier to retain savings for emergencies, career changes and other priorities.
When you may relocate within a few years
If your career, education or family plans could take you to another city, renting gives you greater flexibility. Buying and selling property within a short period can involve substantial transaction costs, and selling may take time. Renting allows you to make location decisions without having to sell a major asset whenever your circumstances change.
When you want to keep your savings accessible
A down payment can use up a large portion of your available savings. Renters can retain that money for emergencies, education, business plans or investments, depending on their priorities. This flexibility can be particularly useful early in a career, when income and long-term plans may still be changing.
However, keeping money available is not the same as building wealth. The financial benefit depends on how that money is managed and whether the investment choices suit the person’s risk tolerance and time horizon.
When you can invest consistently
Consider someone who chooses to rent instead of buying an expensive apartment. They may have money left over after accounting for rent, compared with the combined cost of home loan payments and ownership expenses. If they consistently invest the money they save, their portfolio may grow over time.
But investment returns are not guaranteed. Market performance fluctuates, investments can lose value, and the amount available to invest may change. Renting works best financially when it is part of a deliberate plan rather than simply a way to postpone a purchase.
For a broader look at property as a wealth-building option, read RentOk’s guide on whether real estate is still the best way to grow wealth.
When Buying a House Can Be the Better Choice
Although renting can offer financial flexibility, buying can make sense when your income, savings and long-term plans support it. For some households, ownership offers a combination of financial commitment, stability and control over their living space that renting cannot provide in the same way.
When you plan to stay for the long term
If you expect to live in the same city and home for many years, buying may allow you to spread the upfront transaction costs over a longer period. You also have the opportunity to build equity as you repay the loan.
A holding period of seven years or more is sometimes used as a starting point when evaluating a purchase, but it is not a universal break-even rule. The result depends on the property’s price, rent, loan interest, appreciation, transaction costs and alternative investment returns.
When stability and control matter
Homeownership can provide greater control over your living space. Subject to applicable rules and building restrictions, owners can renovate, personalise and adapt their homes without needing a landlord’s permission. It can also offer stability for families who want to remain in one neighbourhood, keep children in the same school or live close to relatives.
These non-financial benefits have value even when they cannot be expressed as a financial return. For many buyers, the decision is not only about which option produces the highest net worth, but also about the kind of life they want to build.
When you prefer a structured way to build equity
For some buyers, regular home loan repayments create a disciplined route towards ownership. Instead of relying on themselves to invest surplus money every month, they make scheduled repayments that gradually reduce the outstanding principal.
This can be helpful for people who find regular saving difficult. Still, a home loan is a financial commitment, not a substitute for an emergency fund or a diversified investment plan.
Renting vs. Buying: A Financial Comparison
Let’s consider a hypothetical example involving a property worth ₹1 crore. The figures below are illustrative, not current market quotations or a prediction of future returns.
| Factor | Renting | Buying |
|---|---|---|
| Initial cash requirement | Security deposit and moving costs | Down payment and purchase costs |
| Monthly housing expense | Rent and agreed tenant charges | EMI, maintenance and ownership expenses |
| Flexibility to relocate | Generally higher | Usually lower |
| Property ownership | No ownership equity | Equity builds as principal is repaid |
| Maintenance responsibility | Depends on the agreement | Owner bears ownership-related costs |
| Investment flexibility | More capital may remain available | More capital is committed to property |
| Long-term outcome | Depends on rent and investment choices | Depends on loan repayment and property value |
The comparison shows why the EMI-versus-rent calculation is incomplete. A fair evaluation must include the money required upfront, recurring costs, potential investment returns and the value of flexibility.
For a more personalised comparison, a rent vs. buy calculator can help estimate the costs under different assumptions. The results are only as reliable as the inputs, so use realistic figures for rent, property appreciation, interest rates, maintenance and investment returns.

Can Renting and Investing Build More Wealth?
One argument in favour of renting is that the money not used for a down payment can be invested instead. Renters may also invest the difference if their monthly housing costs are lower than the cost of owning an equivalent property.
Suppose a buyer uses ₹20 lakh as a down payment, while a renter keeps that money invested and makes regular additional investments from the money available in their monthly budget. Over a long period, those investments could grow substantially.
However, the comparison needs to account for more than the initial investment. The renter must actually invest the money rather than gradually spend it, and market returns may be higher or lower than expected. The calculation should also include rent increases, taxes, investment fees, home loan costs, property appreciation and the equity the buyer accumulates.
The buyer ends up owning a physical asset, while the renter’s outcome depends on the value of their investment portfolio and future housing costs. The right way to compare the two is to look at net wealth after all relevant costs, rather than assuming that either property appreciation or stock market returns will always win.
What About Property Appreciation and Rental Yields?
Property ownership is often justified by the expectation that the home will become more valuable over time. That can happen, particularly in locations where employment, infrastructure and housing demand grow. However, property appreciation is not guaranteed, and different properties in the same city can perform very differently.
Rental yield is another useful measure, especially when evaluating a property as an investment.
Gross rental yield is calculated by dividing the annual rental income by the property’s purchase price and multiplying the result by 100. For example, if a ₹1 crore property generates ₹25,000 in monthly rent, its annual rental income is ₹3 lakh. Its gross rental yield is therefore 3%.
This does not mean the owner earns a 3% net return. Maintenance, vacancy, repairs, taxes and other costs reduce the amount retained. If the property is financed, loan interest and other financing costs also affect the overall investment outcome.
If you are evaluating property as an income-generating asset rather than a home to live in, RentOk’s guide on how to invest in property for rental income in India explores the factors that affect rental returns.
How Should You Decide Between Renting and Buying in 2026?
Before committing to either option, evaluate your current financial position and your plans for the next several years. A property that looks affordable on paper may become a burden if the EMI leaves little room for savings, while renting may not suit someone who wants long-term stability and has the resources to buy comfortably.
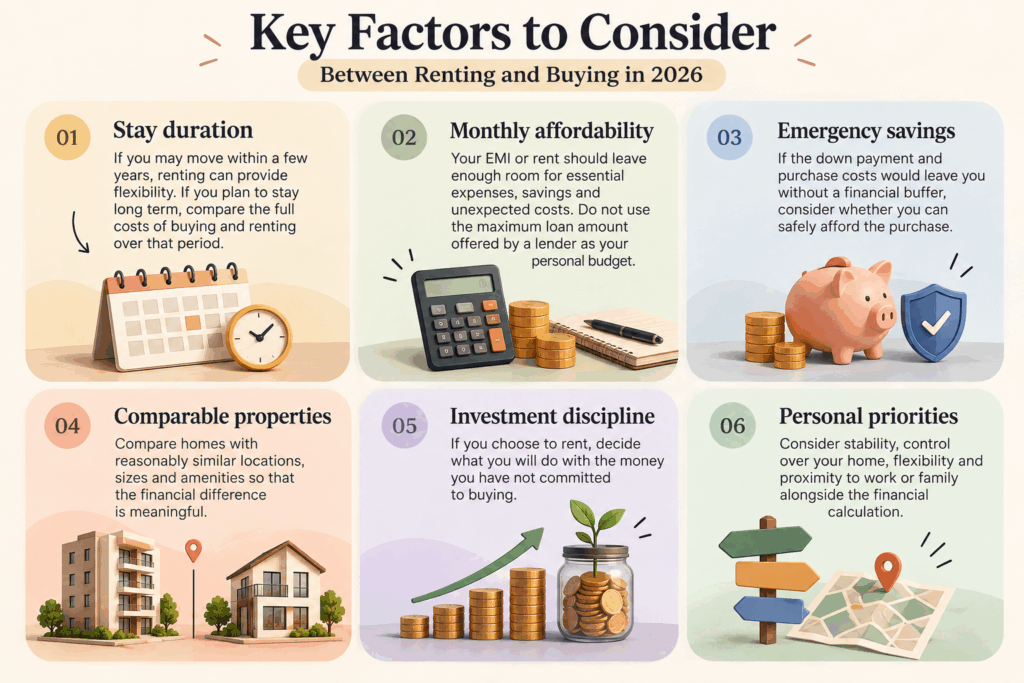
Start by considering these factors:
- Stay duration: If you may move within a few years, renting can provide flexibility. If you expect to stay long term, compare the full costs of buying and renting over that period.
- Monthly affordability: Your EMI should leave enough room for essential expenses, savings and unexpected costs. Do not use the maximum loan amount offered by a lender as your personal budget.
- Emergency savings: If the down payment and purchase costs would leave you without a financial buffer, consider whether you can safely afford the purchase.
- Comparable properties: Compare homes with reasonably similar locations, sizes and amenities so that the financial difference is meaningful.
- Investment discipline: If you choose to rent, decide what you will do with the money you have not committed to buying.
- Personal priorities: Consider stability, control over your home, flexibility and proximity to work or family alongside the financial calculation.
Local housing conditions matter, too. Rent and property prices can differ considerably between neighbourhoods, even within the same city. RentOk’s article on when and why rent in Gurgaon got so expensive offers an example of how local market conditions influence housing costs.
What About Home Loan Tax Benefits?
Tax treatment can influence the renting vs. buying calculation, but it should not be the sole reason to purchase a property. Under applicable Indian tax rules, eligible homeowners may be able to claim deductions relating to home loan interest or principal repayment, depending on factors such as the property’s use, the applicable tax regime and the conditions prescribed by law.
Section 24(b) provides for a deduction for eligible home loan interest, with limits and conditions that differ according to circumstances. Principal repayment may qualify under Section 80C where the relevant provisions and eligibility conditions apply. The availability of these benefits can differ under the old and new tax regimes.
Because tax benefits depend on eligibility, buyers should verify the rules applicable to their financial year and individual circumstances with a qualified tax professional. Any potential tax saving should be considered as part of the broader calculation, rather than treated as a reason on its own to buy a home.
So, Is Renting or Buying Better in 2026?
There is no single answer that applies to every Indian household. Renting may suit you better if you value flexibility, expect to relocate, want to preserve accessible savings or can build a disciplined investment portfolio with the money you do not spend on buying. Buying may suit you better if you have a stable financial position, can afford the upfront costs without exhausting your savings, intend to stay for the long term and value the security and control that ownership can provide.
The important thing is to avoid making the decision solely because homeownership is considered a milestone or because renting is perceived as wasted money. Both options involve costs, and both can support different financial goals.
Before deciding, compare the total cost of ownership with the total cost of renting over the same period, include a realistic investment scenario, and consider the lifestyle you want to maintain. Ultimately, the better housing decision is the one that fits your financial capacity, long-term plans and personal priorities.
Frequently Asked Questions
Find answers to common questions about this topic
About the Author
Ishika Pannu
Ishika Pannu brings you the latest insights and easy-to-apply strategies in property management—helping you simplify renting and grow with RentOk.
You may also like these
Related Articles
1 min read
Rent vs Commute in Gurgaon: How Much Is Convenience Worth?
Written by
Posted on
Ishika Pannu
Oct 9, 2026
1 min read
Bengaluru’s Salary-Rent Gap: Why Are Rents Rising Faster Than Salaries?
Written by
Posted on
Ishika Pannu
Oct 6, 2026
1 min read
GST on PG Rent: What Tenants Pay
Written by
Posted on
Ishika Pannu
Sep 13, 2026
1 min read
When and Why Did Rent in Gurgaon Get So Expensive?
Written by
Posted on
Shivanshi Dheer
Dec 24, 2025
1 min read
What is the Cost of Renovating a PG/Hostel for Setup?
Written by
Posted on
Shivanshi Dheer
Sep 10, 2025
1 min read
Rent Trends in 2025: Delhi vs Bangalore vs Hyderabad
Written by
Posted on
Shivanshi Dheer
Aug 1, 2025
1 min read
Best Areas to Live in Hyderabad for Students and Working Professionals
Written by
Posted on
Shivanshi Dheer
Jun 15, 2025
1 min read
Ultimate List of Amenities for in a PG or Co-Living Space in India
Written by
Posted on
Shivanshi Dheer
Jun 11, 2025
1 min read
What Is the Cost of Living Index And How Is It Calculated?
Written by
Posted on
Shivanshi Dheer
May 29, 2025
1 min read
Best pg manager app in India 2023
Written by
Posted on
Anil Kandpal
Jun 6, 2023
Stay ahead in property management with expert insights
Join thousands of property managers receiving exclusive tips delivered straight to your inbox.
Browse posts by category
Case Study
Cost of Living
Growth
Legal
Market Trends
News
Pg owner app
Property Management
Property Tax
Tech
RentOk
The easiest way to rent and manage your PGs and hostels.
Grievance Officer
Get the app
Contact us
hello@eazyapp.tech
HQ Office
COGROW, BASEMENT F-12/8A
BESIDE HOUSE OF STYLE SALON, SECTOR 28, DLF PHASE 1
GURUGRAM, HARYANA - 122002
South India Office
LUMIODESK COWORKING, 2ND FLOOR, 40, 14TH MAIN RD
BESIDE MC DONALD, 7TH SECTOR, HSR LAYOUT
BENGALURU, KARNATAKA - 560102
©️ 2026 EazyApp Tech Pvt Ltd. All rights reserved


