Property Tax
Can You Claim HRA If You Live in a PG?
Written by
Ishika Pannu
Read Time
11 min read
Posted on
November 18, 2026
Overview
Overview
Can You Claim HRA If You Live in a PG?
Yes, you can claim HRA for PG accommodation if you receive House Rent Allowance through your salary, genuinely pay rent for the place you occupy and choose the old tax regime. You do not need to rent an entire flat. A PG room or shared accommodation can qualify when the arrangement meets the conditions for residential rent.
The important checks concern what you pay for, whose name appears on the documents and how much exemption the calculation allows. This guide covers those checks using the rules for Tax Year 2026–27, from 1 April 2026 to 31 March 2027, with research checked on 18 November 2026. That date matters: Form 124 and the expanded eight-city calculation should not be applied retrospectively to an earlier income period.
When does PG rent qualify for HRA?
The tax test concerns residential accommodation you occupy and rent you actually pay, rather than whether the building calls itself a flat, hostel or PG. Under Schedule III, item 11 of the Income-tax Act, 2025, the accommodation must not belong to you and the allowance must meet the prescribed conditions and limits.
Check your payslip first. A salary credit does not automatically mean your employer pays HRA; look for the allowance in your salary structure. Then confirm that your PG arrangement genuinely involves accommodation rent and that your records identify your stay and payment.
For a shared room, claim your actual rent share, not the full amount that all occupants pay together. Ask for documentation in your name even if one flatmate makes a combined transfer. Keep a clear record of your contribution and the recipient’s acknowledgement.
If your salary has no HRA component, this exemption is not the right route. RentOk’s guide to rent deductions when your employer does not provide HRA explains the separate framework and why the applicable section and declaration depend on the income period.
Can you include meals in your HRA rent figure?
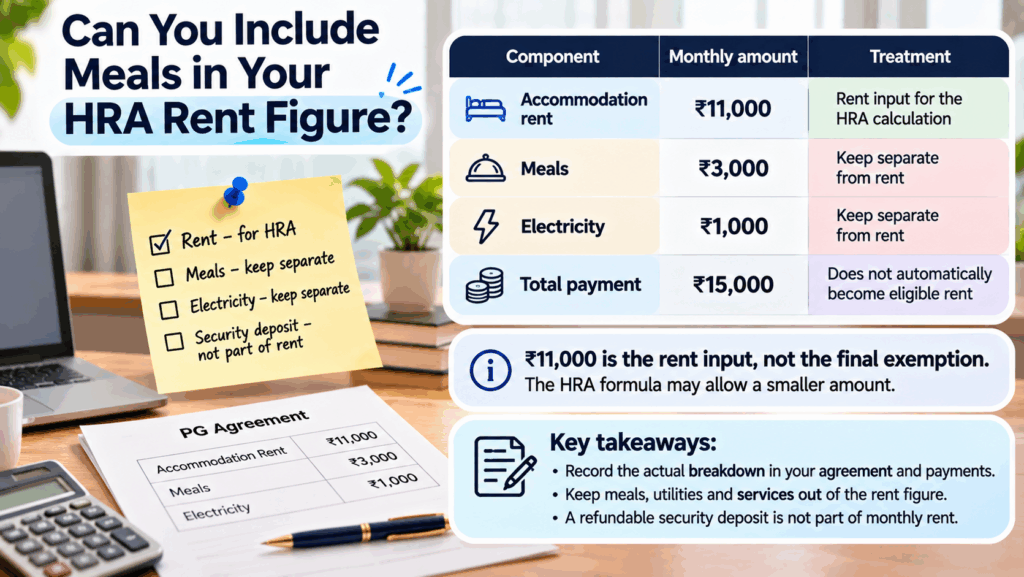
A single PG payment may cover a bed, meals, electricity and other services. The fact that you transfer one amount does not turn every component into accommodation rent. Identify the genuine rental charge and keep separately billed food, utilities and services out of the rent figure you submit for HRA.
Suppose your agreed monthly package contains:
| Component | Monthly amount | Treatment for this example |
|---|---|---|
| Accommodation rent | ₹11,000 | Rent input for the HRA calculation |
| Meals | ₹3,000 | Keep separate from rent |
| Electricity | ₹1,000 | Keep separate from rent |
| Total payment | ₹15,000 | Does not automatically become eligible rent |
Here, ₹11,000 is the rent input, not the final exemption. The formula may allow a smaller amount. A refundable security deposit also serves a different purpose and should not enter the monthly rent figure simply because you paid it at move-in.
Ask the operator to record the actual agreed breakdown in the agreement and payment documents. Do not invent percentages or ask for a false rent-only receipt. If the package is genuinely indivisible, take the contract to payroll or a tax adviser for review. RentOk’s explanation of rent inclusions and extra charges helps you identify the terms to clarify.
Receipts, agreements and landlord details for Form 124
From April 2026, Form 124 replaces Form 12BB for employee claims submitted to the employer. It supports salary-TDS calculations; it is not a separate HRA refund application. The Department’s Form 124 guidance explains its purpose and the employee-to-employer process.
A receipt should explain the payment
For each month, obtain a receipt that connects the money to you and your accommodation. Check these details before submission:
- Names and property: Your name, the landlord or authorised recipient’s name, the complete PG address and a room or bed identifier where useful.
- Rent and period: The accommodation rent received, rental period and payment date, with other charges identifiable separately.
- Acknowledgement and payment trail: The recipient’s signature or suitable authentication, payment mode and available transaction reference.
Keep successful UPI or bank-transfer evidence with the receipt. Cash does not automatically make rent ineligible, but you still need a genuine acknowledgement and the applicable receipt formalities. A generated PDF alone does not prove payment. RentOk’s rent receipt generator guide explains that distinction.
Can you submit HRA without a PG agreement?
Do not rely on blanket advice that receipts always replace an agreement. The Department’s current Form 124 FAQs list a copy of the rent agreement as supporting evidence for HRA. The notified form also lists a house rent agreement as an annexure.
If your PG has not supplied one, request a properly executed document identifying you, the accommodation, rent and relevant dates. Ask payroll about any missing-document issue before its deadline. RentOk’s guide to reading a rent agreement before signing helps you check that the document reflects the actual arrangement.
PAN and relationship disclosure
The landlord’s PAN is required when annual rent exceeds ₹1,00,000. Form 124 also asks about your relationship with the landlord, if any. Disclose it accurately; the form does not invite you to conceal a genuine family relationship.
For an operator-managed PG, establish the correct contractual rent recipient rather than automatically using the building owner’s PAN or a caretaker’s personal PAN. RentOk’s guide to landlord PAN and rent-receipt records explains this documentation issue. Share identification details privately through the employer’s accepted process.
Calculating the HRA exemption on PG rent
Under Rule 279, compare the following amounts for the relevant period and take the lowest, subject to a zero floor:
- Actual HRA received from your employer.
- Rent actually paid minus 10% of the relevant salary.
- 50% of the relevant salary in the eight specified cities, or 40% elsewhere.
The eight cities are Mumbai, Kolkata, Delhi, Chennai, Hyderabad, Pune, Ahmedabad and Bengaluru. The notified Income-tax Rules, 2026 establish these limits from April 2026. Do not extend the city list to a neighbouring municipality merely because you commute to a listed city.
Use the HRA salary base, not CTC or take-home pay. Basic pay and qualifying dearness allowance form the usual starting point; ask payroll to confirm the treatment of commission or other salary components. Recalculate for changes in rent, salary, accommodation or city rather than assuming one annual figure always works.
A monthly example for a Bengaluru PG
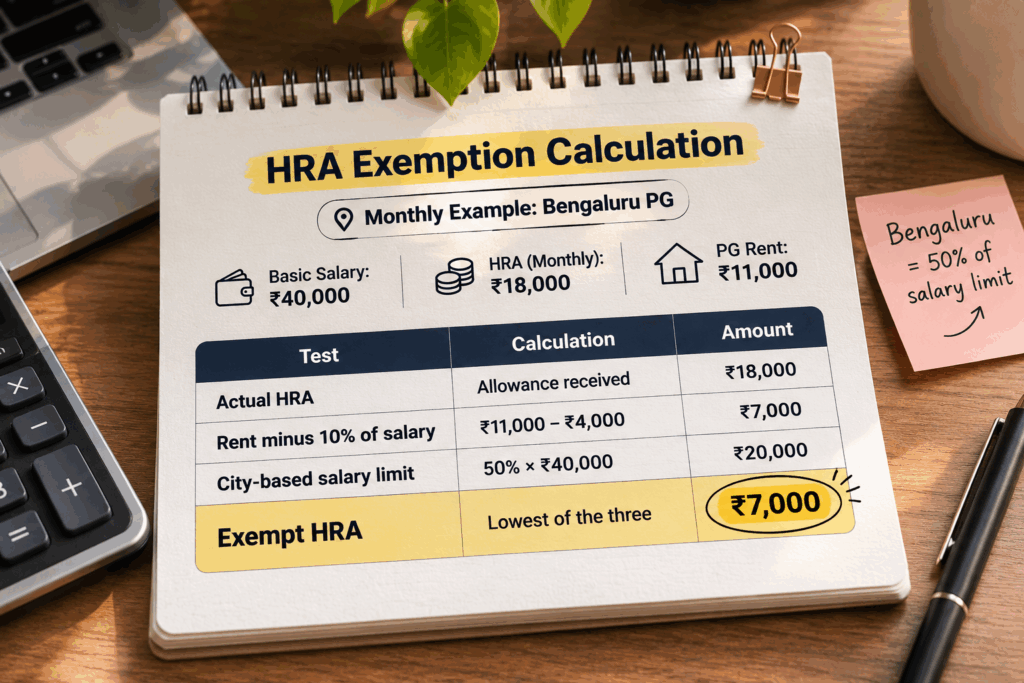
Assume basic salary of ₹40,000, no DA or commission, monthly HRA of ₹18,000, and the ₹11,000 accommodation rent from the earlier example. Assume the same arrangement applies throughout the month.
| Test | Calculation | Amount |
|---|---|---|
| Actual HRA | Allowance received | ₹18,000 |
| Rent minus 10% of salary | ₹11,000 − ₹4,000 | ₹7,000 |
| City-based salary limit | 50% × ₹40,000 | ₹20,000 |
| Exempt HRA | Lowest of the three | ₹7,000 |
The remaining ₹11,000 of monthly HRA is taxable. If all inputs remain unchanged for 12 months, exempt HRA totals ₹84,000. This is an exemption from taxable salary, not a ₹84,000 tax refund; your eventual tax saving depends on the full tax calculation.
Old versus new regime: compare the final tax bill
HRA exemption is available under the old regime, not the new regime. The current Section 202 provisions exclude the relevant Schedule III allowance exemption when computing income under the new regime. Receiving HRA through payroll does not change that restriction.
However, paying substantial PG rent does not automatically make the old regime cheaper. Compare the complete tax bill under both options, accounting for the deductions, exemptions, rates and rebates that apply to you. An HRA exemption reduces taxable income; it does not reduce tax rupee for rupee.
Confirm your payroll declaration and make the appropriate regime choice when filing your return. If you also have business or professional income, check the additional rules for exercising or changing that choice. Keep these decisions separate from whether your landlord can issue a receipt.
For rent paid before 1 April 2026, check the earlier law and forms. AY 2026–27 ordinarily concerns income earned during FY 2025–26; it is not interchangeable with Tax Year 2026–27. Using the eight-city rule merely because an older return is being filed in 2026 can produce the wrong calculation.
Common mistakes that delay or undermine a claim
Most avoidable problems arise when the salary record, agreement, receipts and payment evidence tell different stories. Review them together before submitting your declaration, and ask the issuer to correct genuine errors through a traceable replacement.
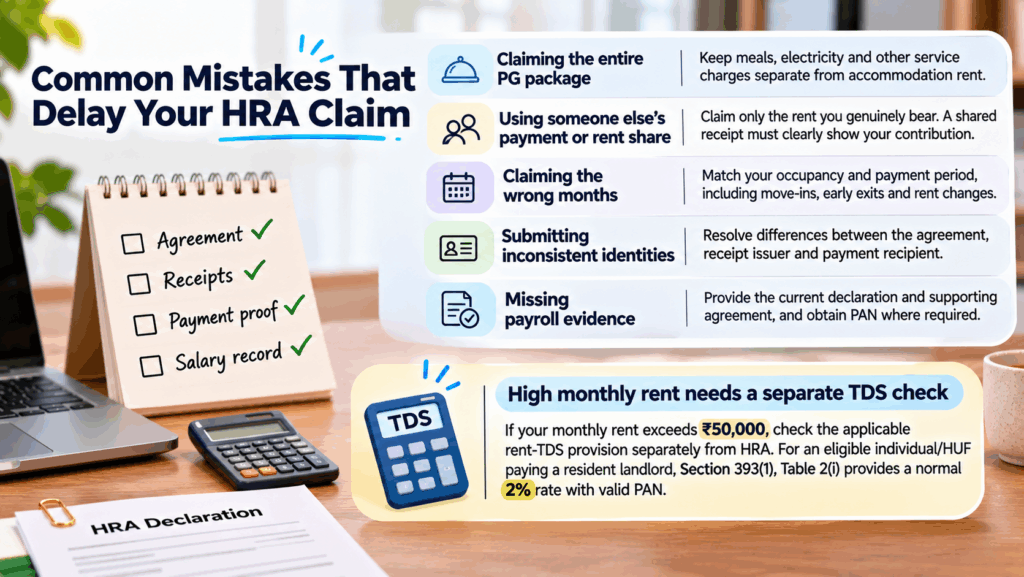
- Claiming the entire PG package: Keep identifiable meals, electricity and other service charges separate from accommodation rent. Do not relabel the bill to increase the exemption.
- Using someone else’s payment or rent share: Claim only the rent you genuinely bear. A receipt covering a room’s combined payments needs a clear connection to your own contribution.
- Claiming the wrong months: Match your occupancy and payment period, including move-ins, early exits and rent changes. Do not reuse a full-year declaration after leaving the PG.
- Submitting inconsistent identities: Resolve differences between the agreement, receipt issuer and payment recipient. A manager collecting on behalf of an operator should have a clear role.
- Missing payroll evidence: Provide the current declaration and supporting agreement, and obtain PAN where required. An attractive receipt template cannot make an unsupported claim valid.
High monthly rent needs a separate TDS check
If your monthly rent exceeds ₹50,000, check the applicable rent-TDS provision separately from HRA. For an eligible individual/HUF paying a resident landlord, Section 393(1), Table 2(i) provides a normal 2% rate with valid PAN; payer category and the recipient’s residential status matter.
Exactly ₹50,000 does not exceed that threshold. The Department’s Form 141 guidance identifies Schedule A for the eligible individual/HUF rent category. RentOk’s guide to Section 393 and Form 141 for rent TDS explains the wider process. Do not assume that an HRA receipt completes your TDS obligations.
How RentOk helps you keep monthly PG rent receipts ready
HRA documentation becomes harder when receipts sit in one chat, the agreement in another and payment references in a bank app. RentOk supports connected resident, agreement and payment records, helping participating PG operators and tenants retrieve the documents behind a rental payment.
- Review the dues before paying: The supported payment page shows the property information and dues breakdown. Check that the charges match your agreement and ask the operator to explain any unclear accommodation or service amount.
- Access payment receipts: The Receipts tab lets tenants view payment details and download or save receipts. Keep the corresponding successful-payment reference with each monthly record.
- Retrieve the completed agreement: RentOk’s agreement workflow makes the final signed PDF available from the resident’s profile. Confirm that your name, premises, dates and rent terms are correct before using it for payroll evidence.
- Prepare a consistent submission: Use the records to reconcile amounts and identify missing months early. Ask the operator for any additional PAN confirmation, rent breakdown or authentication your employer requires.
RentOk’s published payment and agreement workflow documents these capabilities. Confirm which features your property uses. Receipts support your evidence; they do not select your tax regime, calculate an approved exemption or guarantee that payroll accepts the claim.
Conclusion
Living in a PG does not prevent an HRA claim. Eligibility depends on receiving HRA, paying genuine accommodation rent, choosing the old regime and maintaining evidence that supports the amount and period. Separate food and other charges, use the rules for the correct income year and check the calculation before submitting documents.
Get monthly rent receipts on RentOk through your participating PG’s supported payment workflow. Save them alongside your agreement and payment references so your next payroll submission starts with complete records.
Frequently Asked Questions
Find answers to common questions about this topic
About the Author
Ishika Pannu
Ishika Pannu brings you the latest insights and easy-to-apply strategies in property management—helping you simplify renting and grow with RentOk.